Bengaluru AI Fintech Startup Credfix Secures ₹16.1 Crore Seed Funding to Scale Automated Risk Underwriting Engine
By Aarav Sharma | Published October 8, 2026 | 8 min read
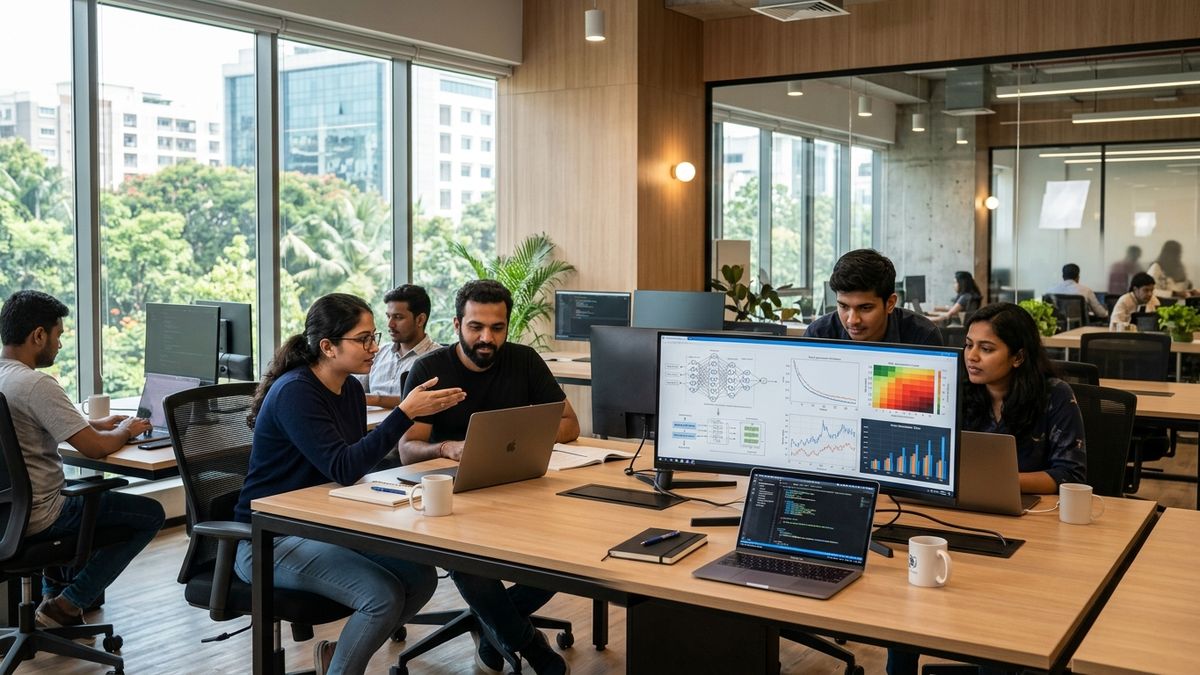
Bengaluru fintech startup Credfix secures ₹16.1 crore in seed funding to expand its real-time AI credit underwriting and fraud analytics engine for institutional lenders.
Bengaluru-based artificial intelligence fintech venture Credfix has raised ₹16.1 crore (approximately $1.9 million) in a seed funding round backed by institutional venture capital investors and prominent financial technology operators. The seed capital will be utilized to accelerate the engineering of its automated credit risk engine, expand its proprietary machine learning risk models, and deepen technical integrations across India's scheduled commercial banks and non-banking financial companies (NBFCs).
The fundraise comes at a juncture when digital lending in India is expanding beyond salaried metro consumers into micro, small, and medium enterprises (MSMEs) and Tier-3 self-employed individuals—segments that historically suffer from an acute lack of formal credit bureau history.
Unlocking Credit for the 'New-to-Credit' Economy via Explainable Machine Learning
For decades, Indian formal lending has relied heavily on conventional credit bureau scores such as CIBIL, Experian, and Equifax. While robust for established corporate borrowers or salaried professionals with lengthy credit card histories, bureau-centric scoring automatically rejects or charges exorbitant risk premiums to over 150 million creditworthy Indians who operate cash-flow-rich informal or micro-enterprises.
Credfix bridges this structural credit asymmetry. The startup has developed an explainable machine learning platform that ingests consent-backed data through the Reserve Bank of India's (RBI) Account Aggregator (AA) framework. By analyzing bank statement velocity, Goods and Services Tax (GST) e-way bills, merchant QR payment cadence, and recurring utility bills, Credfix produces dynamic credit scores in under 1.5 seconds.
"True financial inclusion cannot rely on legacy, backwards-looking credit scores that penalize entrepreneurs for lacking credit cards,"stated Credfix leadership. "By applying multi-modal machine learning to real-time cash flow telemetry, we enable lenders to originate high-quality loans with verifiable fraud protection."
This focus on modern financial infrastructure mirrors capital expansion seen across the ecosystem, including wealthtech platform Zomint raising ₹36 crore from Lightspeed and Vijay Shekhar Sharma funding native AI model builders.
Underwriting Paradigms: Legacy Scoring vs Credfix AI Intelligence
The table below contrasts Credfix's AI risk engine with traditional bureau models and manual NBFC underwriting:
| Evaluation Dimension | Legacy Credit Bureau Scoring | Manual NBFC Underwriting | Credfix AI Multi-Modal Engine |
|---|---|---|---|
| Data Ingestion Model | Historical Debt Repayment Only | Physical Paper Statements & Visits | Consent-Backed Account Aggregator APIs |
| Turnaround Time (TAT) | Minutes (Bureau Query Only) | 3 to 7 Business Days | Sub-2 Seconds Automated Decisioning |
| Thin-File Coverage | Very Poor (High Rejection Rates) | Moderate (Labor-Intensive) | Superior (Multi-Source Cash Flow Analysis) |
| Fraud Detection | Basic Identity Verification | Manual Visual Document Audit | Deep Neural Anomaly & Tamper Detection |
| Default Prediction Accuracy | Moderate on Informal Segments | Variable (Subjective Bias) | 28% Improvement in Gini Coefficient |
| Auditability & Explainability | Black-Box Numeric Score | Discretionary Branch Manager Note | SHAP/LIME Explainable Factor Breakdown |
Account Aggregator Integration and Real-Time Telemetry
Credfix's technical breakthrough lies in its automated data-cleaning and feature-engineering pipeline. Ingesting raw Account Aggregator data from multiple banks often presents fragmented transaction descriptions, inconsistent categorization, and noisy metadata.
Credfix's natural language processing (NLP) models normalize thousands of disparate bank narration strings into distinct financial categories—distinguishing between organic business revenues, circular bank-to-bank transfers, intra-family loans, and bounce charges. The platform synthesizes over 400 financial telemetry features to compute an audited default probability score.
Fraud Vector Mitigation and Institutional Governance
Beyond creditworthiness, digital lending platforms face an escalating wave of sophisticated fraud, including synthetic identities, forged digital salary slips, and organized mule accounts.
Credfix incorporates automated image forensics and computer vision models that verify document metadata and detect pixel tampering on submitted PDF bank statements. Furthermore, its graph neural networks (GNNs) analyze transaction topologies to flag circular fund routing between co-conspiring borrower entities, protecting partner NBFCs before capital is disbursed.
Future Outlook for India's AI-Powered Credit Landscape
With ₹16.1 crore in seed capital, a high-caliber technical team based in Bengaluru, and accelerating customer traction among mid-market NBFCs, Credfix is positioned to become a foundational risk infrastructure provider. As India's digital lending market surpasses $350 billion by 2030, automated, explainable AI platforms like Credfix will play an indispensable role in maintaining systemic financial stability while expanding credit to millions of underserved Indian enterprises.
Frequently Asked Questions
What does Credfix do and how much funding did it raise?
Credfix is a Bengaluru-based AI fintech platform that raised ₹16.1 crore in seed financing to provide digital lenders, banks, and NBFCs with automated risk underwriting, fraud detection, and alternative credit intelligence.
How does Credfix's AI engine evaluate borrowers without credit bureau scores?
Credfix ingests consent-backed alternative data via the RBI's Account Aggregator framework, incorporating GST returns, merchant cash flow data, recurring utility payments, and behavioral metrics through gradient-boosted decision trees and neural networks.
Who are the target clients for Credfix's platform?
The platform is built for scheduled commercial banks, retail NBFCs, micro-finance institutions (MFIs), and embedded finance fintech applications seeking to reduce non-performing assets (NPAs) while improving loan approval speeds.
How does Credfix ensure compliance with RBI digital lending directives?
The platform operates strictly as a technology service provider (TSP) without balance sheet exposure, adhering to RBI digital lending guidelines by enforcing end-to-end data localization, encryption, and explicit consumer consent architecture.
Primary Sources & Official References
- Reserve Bank of India (RBI): Guidelines on Digital Lending and Account Aggregator Ecosystem
- NITI Aayog: Report on Digitally-Enabled Lending for Indian MSMEs
- Credfix Technologies Private Limited: Technical Platform and Seed Round Announcement
- Fintech Convergence Council (FCC): Annual Industry Report on Credit Infrastructure